The analysts’ new price target sees ISRG shares returning over the next 12–18 months to the $500-plus-per-share levels they traded at through much of 2025.
ISRG shares were down slightly to $399.78 apiece by midday trading today; the S&P 500 was up slightly.
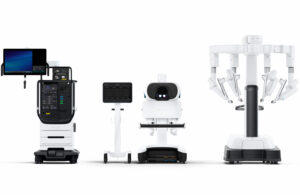
The maker of da Vinci soft-tissue robotic surgery systems is getting a new major competitor in the U.S.: Johnson & Johnson, which secured long-awaited FDA de novo authorization for its Ottava system last month.
Medtronic, meanwhile, is seeking expanded U.S. indications for its Hugo robotic surgery system after receiving the first FDA clearance for the system late last year.
However, the Oppenheimer analysts — Suraj Kalia, Shaymus Contorno, and Jakub Mlejnek — say that their field checks found unique workflow challenges for Ottava, which incorporates four robotic arms into a standard-size surgical table. According to the analysts, the system design means that there’s arm deployment in non-sterile environment after an anesthetized patient placed on the table, with the need to re-sterilize the system with bodily fluid leakage on the table.
The analysts also noted that Hugo takes up more real estate in an operating room than da Vinci. (Medtronic officials, however, have argued that Hugo is more flexible because of its modular, multi-quadrant platform.)
The analysts’ conclusion is that U.S. competition is not a factor in Intuitive’s continued growth, though the need for Intuitive to enter the fast-growing ambulatory surgery space will present unique tactical challenges. They think the main competition will occur outside the United States — in China — from homegrown systems such as Medbot, Kangduo, and Toumai.
Other analysts shared similar views when Intuitive released its second-quarter earnings last month. Despite Street-beating earnings and revenue, investors appeared to want more.
Said BTIG analysts Ryan Zimmerman and Iseult McMahon: “On balance, the quarter itself looked fine, though the combination of softer U.S. da Vinci procedure growth (~12%) and limited visibility into upside for the remainder of FY26 that continues to weigh on the stock.”
The BTIG analysts, though, stuck to their Buy rating on ISRG shares on the conviction that Intuitive has a strong long-term position in the robotic surgery market. They mentioned a recent survey that reinforces the company’s dominant place in the surgical robotics market “with little sign of erosion.”
Baird analysts David Rescott and Tommy Han stuck to their Outperform rating after the earnings release, but also noted headwinds from Affordable Care Act insurance subsidies expiring: “Thus, while the elements of ISRG’s longer-term value-creation story remain attractive, as ISRG begins to contend with ACA uncertainty, we expect shares to remain under pressure.”
Meanwhile, Needham & Co. analysts Mike Matson, David Saxon and Joseph Conway placed more stock in competion after the Society of Robotic Surgery’s annual meeting last month, noting that there are 36 companies with competing soft tissue robots around the world. “While we expect ISRG to remain dominant, we see potential for Johnson & Johnson … and Medtronic .. to capture moderate market share in the US and for local companies (from China, India, etc.) to capture significant market share in the developing world.”
More on MassDevice and Medical Design & Outsourcing:
Download our free MassDevice Surgical Robotics Special Report.
SRS 2026 recap: The biggest surgical robot stories
The Intuitive da Vinci 5’s 10,000x computing leap: Here’s what it means