 Medtronic
(NYSE: MDT)
pulsed-field ablation (PFA) offerings enabled the medtech giant to more than double its U.S. Cardiac Ablation Solutions sales, helping to fuel a Street-beating Q2.
With Medtronic also upping its full-year revenue guidance and the lower end of its EPS forecast, investors responded by sending MDT shares up more than 5% to $101.54 apiece in morning trading today.
“We delivered a strong second quarter,” Medtronic Chair and CEO Geoff Martha said during the company’s earnings call with analysts this morning. “Both our revenue and EPS beat expectations. Looking across our business, procedure volumes and end markets are robust, and we’re bringing Medtronic’s full capabilities to bear as we launch innovative technologies and execute ahead of plan in some of the most attractive and fast-growing end markets in medtech.”
Medtronic earned $1.38 billion, or $1.07 per share, on $8.96 billion in sales for the quarter ended Oct. 24, 2025. The bottom line was up 8.1% and the top line was up 6.6% compared with last year’s second quarter.
Adjusted to exclude one-time items, Medtronic’s EPS was $1.36. The result was nickel ahead of the Wall Street analyst consensus of $1.31 EPS and $8.86 billion in revenue.
Medtronic is upping its full-year organic revenue growth guidance to 5.5% from the previous 5.0%. The full-year adjusted EPS guidance is now $5.62–5.66 versus the previous $5.60–5.66.
Said Martha: “We’re positioning ourselves for even greater acceleration in revenue growth in the back half of the year and beyond, and our momentum is fueled by our enterprise growth drivers, including our PFA franchise for AFib, [Symplicity Spyral renal denervation] for hypertension, Hugo and soft tissue robotics, and Altaviva for incontinence. … And at this pivotal inflection point in our growth journey, we recognize the need to capitalize on the incredible market opportunities before us.”
Medtronic is scaling manufacturing and increasing operational spending to sustain momentum, Martha said.
“Overall, we’ve shifted to a growth mindset,” he said. “Besides our organic programs, we’re focused on pursuing tuck-in M&A and executing strategic portfolio management.”
More at Medical Design & Outsourcing: Medtronic tech takeaways on PFA, RDN, M&A and R&D from top executives
Affera pulsed-field ablation is a major growth driver for Medtronic
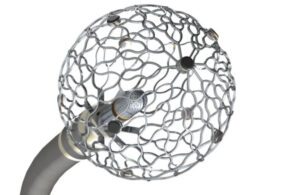
“We’re winning share as our PFA franchise grew over 300% in the U.S., as well as in international markets. This was based on the strength of our Affera mapping system and our Sphere-9 dual-energy and high-density mapping catheter,” Martha said.
“Physicians tell us that they appreciate not only the shorter procedure times that they’re seeing with Affera, but increasingly, they’re calling out its outstanding durability as well. Demand continues to be extremely high, as we hear repeatedly from customers that they want to purchase additional Affera systems to expand into even more of their labs. In the vast majority of instances, when a new Affera system goes into a lab, we take the majority of the AF procedure share in that lab.”
Next up is the Affera Sphere-360, an investigational single-shot mapping and ablation catheter that uses pulsed-field energy to treat patients with paroxysmal AFib. Medtronic has submitted an application for an investigational device exemption (IDE) with the FDA so that it can get approval to start Sphere-360’s U.S. pivotal trial in the present quarter, according to Martha.
Medical Design & Outsourcing: Medtronic’s Sphere-360 PFA catheter has some new tricks
Medtronic officials are also excited about renal denervation, Altaviva for urinary incontinence, and Hugo robotic surgery
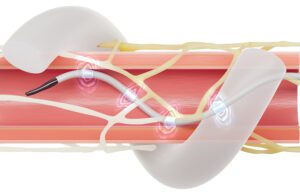
Positive data continues to come out about the system and CMS issued its final National Coverage Determination (NCD) on RDN. Martha said Medtronic also scored wins in the second quarter with private payers, including HCSC, Regence, and several Blue Cross Blue Shield plans that collectively cover 30 million lives.
“We have supply, we’ve ramped up physician training and market development activities, with many hospitals initiating Symplicity programs across the country, and now we’re increasing our consumer awareness programs,” Martha said. “As a result, we expect our revenue to pick up in the back half of the fiscal year and ramp over the next few quarters and meaningfully contribute to Medtronic for years to come.”

Martha said the first weeks of the Altaviva launch have been positive. “Physician training programs are oversubscribed, and we’re expanding training capacity to meet this demand. Physicians are stacking cases, and early media coverage has driven a surge in consumer search activity. Altaviva is a simple option to treat urinary urges and involuntary leaks, which affect 16 million people in the U.S.”
Year-over-year in the second quarter, Medtronic’s Cardiovascular business grew 10.8% to $3.44 billion, Neuroscience was up 4.5% to $2.56 billion, Medical Surgical was up 2.1% to $2.17 billion, and Diabetes was up 10.3% to $757 million.

“In the back half of this fiscal year, we expect the FDA to approve Hugo with a urology indication, and we’ll start our entrance in the U.S.,” he said. “We also continue to make progress on expanding indications.”
Meanwhile, plans to separate the Diabetes business into an independent company called MiniMed remain on track.
Drug Delivery Business News:
Said Martha: “We’re executing on our commitments. You can see it in our numbers, and with every quarter we’re picking up more momentum.”
Needham & Co. analysts, however, are maintaining a Hold rating on MDT shares until they see continued positive news.
Said Mike Matson and his colleagues at Needham & Co.: “We believe that MDT is in the early stages of a strong product cycle, and we are encouraged by its improved growth in F26Q2, but we maintain our Hold rating until there are more signs that its organic growth is seeing meaningful and sustainable acceleration.”
William Blair analysts, led by Brandon Vazquez, stuck by their Market Perform rating, saying they need to see multiple drivers align. “While the pipeline is encouraging, at the end of the day, we are still in mid-single-digit revenue growth, and investments have offset potential EPS upside.”